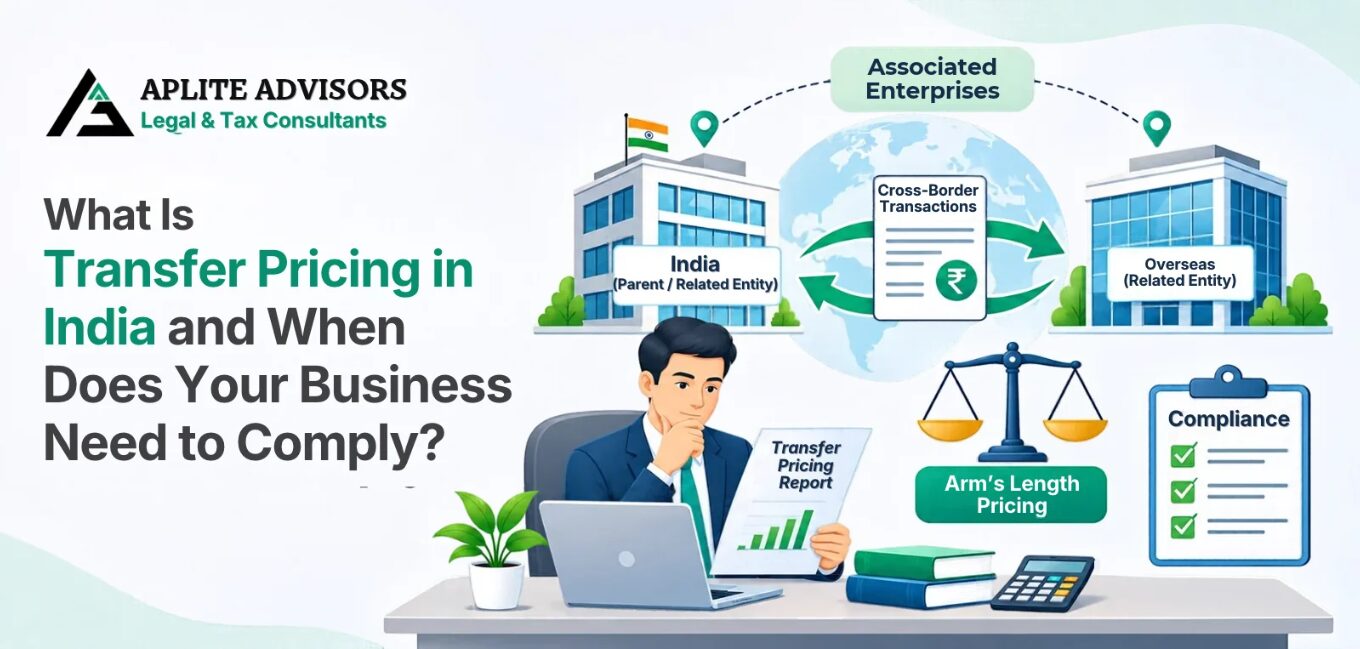
As Indian businesses expand internationally, transactions between parent companies, subsidiaries, group entities and other related parties are becoming increasingly common. These transactions may involve the purchase of goods, software development services, management fees, royalty payments, loans or shared business expenses.
However, when related entities operate in different countries, the prices charged between them can affect how much taxable profit is reported in each jurisdiction. This is why tax authorities closely monitor such transactions through transfer pricing regulations in India.
Transfer pricing in India is a tax compliance framework that requires certain transactions between associated enterprises to follow the arm’s length principle. Businesses covered by these provisions must determine appropriate transaction prices, maintain prescribed documentation and fulfil annual reporting requirements.
Understanding transfer pricing compliance is particularly important for Indian subsidiaries of multinational companies, businesses providing services to overseas group entities and Indian companies entering into related-party financial or commercial arrangements.
This article explains how transfer pricing works, when the rules apply, the documentation required and the compliance framework under India’s Income-tax Act, 2025.
What Is Transfer Pricing?
Transfer pricing refers to the pricing of goods, services, intellectual property, financial arrangements and other transactions between associated enterprises or related entities.
In simple terms, when two companies belonging to the same business group transact with each other, the price charged for that transaction is called the transfer price.
For example, consider a multinational company headquartered in the United States with an Indian subsidiary.
The Indian subsidiary may:
- Purchase products from its US parent company.
- Provide software development services to another group entity.
- Pay royalty for using a group-owned brand or technology.
- Receive an intercompany loan.
- Pay management or administrative service fees.
The prices charged for these transactions can influence the profits reported by each entity and the tax payable in the respective countries.
Transfer pricing regulations ensure that covered transactions are priced appropriately and do not artificially shift profits between related entities to obtain an unintended tax advantage.
Why Do Transfer Pricing Regulations Exist?
Governments introduce transfer pricing rules to ensure that profits are appropriately allocated to the countries where relevant business activities and economic contributions take place.
Without appropriate pricing controls, multinational groups could potentially manipulate intercompany prices to report higher profits in lower-tax jurisdictions and lower profits in higher-tax jurisdictions.
The purpose of transfer pricing rules is to:
- Prevent artificial shifting of taxable profits.
- Ensure fair allocation of income between related entities.
- Improve transparency in international business transactions.
- Establish consistent pricing standards.
- Reduce tax avoidance opportunities.
- Support accurate tax reporting.
In India, the principal transfer pricing framework is contained in Chapter X of the Income-tax Act, 2025, for Tax Years beginning on or after 1 April 2026.
Understanding the Arm’s Length Principle
The arm’s length principle is the foundation of transfer pricing regulations.
It means that a transaction between associated enterprises should generally be priced as if the parties were independent businesses dealing with each other under comparable circumstances.
In other words, related companies should not set arbitrary prices simply because they belong to the same business group.
Example of Arm’s Length Pricing
Suppose an Indian company purchases a product from its overseas associated enterprise for ₹10 lakh.
Comparable independent suppliers sell a similar product under comparable commercial conditions for approximately ₹12 lakh.
The difference may raise a transfer pricing question. The Indian company may need to examine whether the difference is justified by factors such as product quality, volume discounts, contractual terms, market conditions, functions performed or risks assumed.
The comparison should not be based on price alone. Businesses must consider whether the transactions are sufficiently comparable.
Why Is Benchmarking Important?
Benchmarking involves comparing a controlled transaction between associated enterprises with comparable uncontrolled transactions between independent businesses.
A benchmarking analysis generally considers:
- Nature and characteristics of goods or services.
- Functions performed by each enterprise.
- Assets employed in the transaction.
- Risks assumed by the parties.
- Contractual terms.
- Economic and market conditions.
- Geographic and industry differences.
This analysis helps businesses determine an appropriate arm’s length price and support their transfer pricing position with relevant evidence.
When Do Transfer Pricing Rules Apply in India?
Transfer pricing applicability in India depends primarily on the nature of the transaction, the relationship between the parties and the relevant statutory conditions.
The Indian framework broadly covers two categories:
- International transactions between associated enterprises.
- Specified domestic transactions that fall within the statutory definition and monetary threshold.
International Transactions Between Associated Enterprises
Under Section 163 of the Income-tax Act, 2025, an international transaction generally means a transaction between two or more associated enterprises where at least one enterprise is a non-resident.
The provisions can apply to transactions involving:
Purchase or Sale of Goods
An Indian company purchasing raw materials, finished products or components from an overseas group company may be covered.
Provision of Services
An Indian subsidiary providing software development, IT support, accounting, customer support or business process services to a foreign associated enterprise may fall within the transfer pricing framework.
Royalty and Intellectual Property Transactions
Payments for using trademarks, patents, copyrights, software, technical know-how or other intellectual property may require transfer pricing analysis.
Loans and Financial Arrangements
Intercompany loans, interest payments, guarantees and other financial arrangements between associated enterprises can be covered.
Cost-Sharing and Management Services
Payments for shared administrative services, management support, research and development, technical assistance and common business facilities may also be subject to transfer pricing requirements.
Important: International transactions covered by the transfer pricing provisions are not subject to a general minimum monetary threshold. Even relatively small transactions may require consideration of the applicable pricing, documentation and reporting obligations.
Specified Domestic Transactions
Transfer pricing rules also cover certain qualifying domestic transactions under the category of Specified Domestic Transactions (SDTs).
These are not all related-party transactions. Only transactions falling within the statutory categories are covered.
Under Section 164 of the Income-tax Act, 2025, specified domestic transactions include certain transactions connected with:
- Eligible business arrangements involving transfers of goods or services.
- Transactions between eligible businesses and other persons under specified deduction-related provisions.
- Certain transactions involving related persons under applicable provisions.
- Other transactions specifically prescribed under the law.
The aggregate value of qualifying specified domestic transactions must exceed ₹20 crore in a tax year for the specified domestic transaction provisions to apply.
This threshold is particularly important for Indian businesses with related domestic entities or transactions covered by the relevant tax deduction provisions.
International Transactions vs Specified Domestic Transactions
| Comparison | International Transactions | Specified Domestic Transactions |
| Parties involved | Associated enterprises, with at least one non-resident | Parties or arrangements covered by the specified domestic transaction provisions |
| Geographic scope | Cross-border | Within India |
| Monetary threshold | No general minimum threshold | Aggregate qualifying transactions must exceed ₹20 crore in the tax year |
| Applicable framework | Sections 161–173 of the Income-tax Act, 2025 | Sections 161–173 of the Income-tax Act, 2025 |
| Pricing requirement | Arm’s length principle | Arm’s length principle |
| Reporting | Accountant’s report in Form No. 48 for the new framework | Accountant’s report in Form No. 48 for the new framework |
Who Are Associated Enterprises Under Indian Transfer Pricing Rules?
The meaning of an Associated Enterprise (AE) is important because transfer pricing provisions generally apply to transactions between enterprises that meet the statutory relationship tests.
Under Section 162 of the Income-tax Act, 2025, enterprises may be treated as associated where one participates directly or indirectly in the management, control or capital of the other, or where specified relationships and conditions exist.
These relationships can arise through:
- Direct or indirect shareholding.
- Common ownership or control.
- Significant voting power.
- Loans and financial dependence.
- Guarantees for borrowings.
- Appointment of directors or management.
- Dependence on intellectual property or technical know-how.
- Specified supply or sales arrangements.
- Other relationships prescribed under the law.
Practical Examples of Associated Enterprises
Parent Company and Subsidiary
An Indian subsidiary is owned or controlled by a foreign parent company. Transactions between them may fall under the associated enterprise provisions.
Two Companies With Common Ownership
Two businesses may be treated as associated enterprises where the same person or group participates in the management, control or capital of both, subject to the statutory tests.
Group Companies Providing Services to Each Other
An Indian company providing accounting, software development or management services to an overseas group entity may enter into an international transaction.
Financially Connected Enterprises
An enterprise providing a qualifying level of financial support or guarantees to another enterprise may establish an associated enterprise relationship under the relevant provisions.
Businesses should review the statutory relationship tests rather than relying only on whether two companies describe themselves as group companies or related parties.
Common Examples of Transfer Pricing Transactions
Many businesses may undertake transactions covered by transfer pricing regulations in India without recognising their reporting obligations.
Some common examples include:
| Transaction | Practical Example |
| Purchase of goods | An Indian subsidiary purchases machinery or raw materials from its overseas parent company. |
| Software development services | An Indian IT company develops software for an associated enterprise in the United States. |
| Royalty payments | An Indian company pays a foreign group entity for using its trademark or proprietary technology. |
| Intercompany loans | A foreign parent company provides funding to its Indian subsidiary. |
| Management fees | An Indian company pays its overseas group headquarters for management support. |
| Cost-sharing arrangements | Multiple group entities share expenses for research, technology or administrative services. |
| Corporate guarantees | One associated enterprise provides a financial guarantee for another group entity’s borrowing. |
Each transaction requires an assessment of its nature, commercial purpose, contractual terms and applicable transfer pricing requirements.
Methods Used to Determine Arm’s Length Price
Under Section 165 of the Income-tax Act, 2025, the arm’s length price is determined using the most appropriate method based on the nature of the transaction and relevant circumstances.
The law recognises six methods.
Comparable Uncontrolled Price Method (CUP)
The Comparable Uncontrolled Price Method compares the price charged in a controlled transaction with the price charged in a comparable transaction between independent parties.
It may be appropriate where reliable comparable transactions are available.
Example: An Indian company purchases a product from its associated enterprise and also purchases a comparable product from an independent supplier under similar conditions. The independent transaction may provide a reference for benchmarking.
Resale Price Method (RPM)
The Resale Price Method is commonly considered when goods purchased from an associated enterprise are resold to independent customers without significant value addition.
The resale price is reduced by an appropriate gross margin and relevant costs to estimate an arm’s length purchase price.
Example: An Indian distributor purchases products from an overseas group company and resells them to independent retailers.
Cost Plus Method (CPM)
The Cost Plus Method determines an appropriate price by adding a comparable gross profit mark-up to the costs incurred in providing goods or services.
It may be suitable for manufacturing, processing or certain service arrangements.
Example: An Indian contract manufacturer produces components for an overseas associated enterprise. Its costs and an appropriate mark-up are evaluated to determine the arm’s length price.
Profit Split Method (PSM)
The Profit Split Method is useful where associated enterprises make significant and integrated contributions to a transaction and their activities cannot be reliably evaluated separately.
The combined profits from the relevant transaction are divided between the associated enterprises using an economically appropriate allocation basis.
Example: Two group companies jointly develop valuable intellectual property and contribute significant functions, assets and risks.
Transactional Net Margin Method (TNMM)
The Transactional Net Margin Method compares the net profit margin earned from a controlled transaction with the margins earned by comparable independent businesses or transactions.
It is widely considered where reliable gross-margin comparisons are difficult to establish.
Example: An Indian IT services provider earns revenue from an overseas associated enterprise. Its operating margin may be compared with that of independent IT service providers performing similar functions and assuming comparable risks.
Other Method
The Other Method allows the use of a prescribed method based on the price that has been charged or paid, or would have been charged or paid, in a comparable uncontrolled transaction under similar circumstances.
It may be considered when the other prescribed methods are not the most appropriate or reliable for the transaction.
How Should a Business Select the Most Appropriate Method?
There is no single transfer pricing method that works for every transaction.
The selection should consider:
- The nature of the transaction.
- Functions performed by each associated enterprise.
- Assets employed and risks assumed.
- Availability and reliability of comparable data.
- Commercial circumstances.
- The level of comparability that can reasonably be achieved.
A well-supported method selection is an important part of transfer pricing documentation services and benchmarking analysis.
Transfer Pricing Documentation and Compliance Requirements
Businesses covered by transfer pricing provisions must maintain supporting information and documents to demonstrate that their related-party transactions comply with the arm’s length principle.
Under Section 171 of the Income-tax Act, 2025 and Rule 84 of the Income-tax Rules, 2026, prescribed information and documentation must be maintained.
Important Transfer Pricing Documents
Details of Associated Enterprises
Maintain ownership structures, group relationships, business details and relevant information about associated enterprises involved in the transactions.
Details of International and Domestic Transactions
Record the nature, terms, prices, values and quantities of goods or services transferred between associated enterprises.
Functional, Asset and Risk Analysis (FAR)
A FAR analysis explains:
- Functions performed by each entity.
- Assets employed by each entity.
- Risks assumed by each entity.
This analysis helps explain how profits should be allocated between the associated enterprises.
Benchmarking and Comparable Transaction Analysis
Maintain details of comparable uncontrolled transactions, relevant market data, financial information and comparability adjustments.
Transfer Pricing Method Selection
Document the methods considered, the method selected as most appropriate and the reasons for choosing it.
Supporting Agreements and Financial Records
Maintain intercompany agreements, invoices, payment records, financial statements, cost allocation workings and other relevant supporting documents.
Adjustments and Pricing Records
Record any adjustments made to align transaction prices with the determined arm’s length price.
How Long Should Transfer Pricing Documents Be Maintained?
Under Rule 84 of the Income-tax Rules, 2026, the prescribed information and documents are generally required to be maintained for nine years from the end of the relevant tax year, subject to the applicable provisions.
Businesses should also ensure that supporting documents can be produced when requested by the tax authorities within the prescribed time.
Transfer Pricing Compliance Under the Income-tax Act in India
One important development for businesses is the introduction of the Income-tax Act, 2025, which came into effect on 1 April 2026.
This means businesses must distinguish between transactions relating to periods governed by the Income-tax Act, 1961 and those governed by the new legislation.
Compliance for FY 2025–26
For transactions undertaken during FY 2025–26, the Income-tax Act, 1961 continues to govern the relevant transfer pricing obligations.
The key provisions include:
- Section 92: Computation of income having regard to the arm’s length price.
- Section 92A: Meaning of associated enterprise.
- Section 92B: Meaning of international transaction.
- Section 92BA: Meaning of specified domestic transaction.
- Section 92C: Methods for determining arm’s length price.
- Section 92D: Maintenance and furnishing of information and documents.
- Section 92E: Accountant’s report requirement.
The prescribed accountant’s report for this period is Form 3CEB.
The new Act does not automatically change the compliance forms for earlier periods merely because the filing date falls after 1 April 2026.
Compliance for Tax Year 2026–27 Onwards
For Tax Years beginning on or after 1 April 2026, the transfer pricing provisions are contained in Sections 161–173 of the Income-tax Act, 2025.
The important provisions include:
| Provision | Subject |
| Section 161 | Computation of income having regard to arm’s length price |
| Section 162 | Meaning of associated enterprise |
| Section 163 | Meaning of international transaction |
| Section 164 | Meaning of specified domestic transaction |
| Section 165 | Determination of arm’s length price |
| Section 166 | Reference to Transfer Pricing Officer |
| Section 168 | Advance Pricing Agreement |
| Section 170 | Secondary adjustment in certain cases |
| Section 171 | Maintenance, keeping and furnishing of information and documents |
| Section 172 | Report from an accountant |
| Section 173 | Definitions relevant to transfer pricing |
Form No. 48: The New Accountant’s Report
Under Section 172 of the Income-tax Act, 2025 and Rule 85 of the Income-tax Rules, 2026, every person who has entered into an international transaction or specified domestic transaction during a tax year must obtain and furnish an accountant’s report.
The prescribed form is Form No. 48.
Form No. 48 replaces Form 3CEB for the new tax framework.
The form includes information about:
- Particulars of the taxpayer.
- Aggregate international and specified domestic transactions.
- Associated enterprises and relevant transaction details.
- Transactions covered by Advance Pricing Agreements.
- Determination of arm’s length price.
- Relevant pricing adjustments and documentation details.
Form No. 48 is filed electronically through the Income Tax e-Filing portal.
Important distinction: For FY 2025–26, use the applicable old-law framework and Form 3CEB. For Tax Year 2026–27 onwards, use the new framework and Form No. 48.
Important Transfer Pricing Reporting Deadlines
Timely reporting is an essential part of transfer pricing compliance.
Under the new framework, Section 172 read with Rule 85 requires the accountant’s report to be furnished at least one month before the applicable due date for filing the income tax return under Section 263(1).
The corresponding reporting requirement under Section 92E of the Income-tax Act, 1961 also generally requires Form 3CEB to be furnished at least one month before the applicable income tax return due date.
Why Should Businesses Start Early?
Transfer pricing documentation involves financial analysis, comparable data, agreements and transaction-level information. Preparing everything close to the filing deadline can increase the risk of errors and incomplete reporting.
Businesses should plan the following activities in advance:
- Identify all associated enterprises.
- Compile international and qualifying domestic transaction details.
- Review intercompany agreements and invoices.
- Complete functional, asset and risk analysis.
- Conduct benchmarking and select the most appropriate method.
- Prepare supporting documentation.
- Coordinate with the appointed accountant for the prescribed report.
- Review and submit the report within the applicable deadline.
The exact return due date and reporting deadline should be confirmed for the relevant tax year, taxpayer category and any applicable CBDT extensions.
Consequences of Transfer Pricing Non-Compliance
Failure to follow transfer pricing requirements can result in financial penalties, tax adjustments and increased scrutiny.
The consequences depend on the specific nature of the default and the applicable tax year.
Penalty for Failure to Maintain or Report Information
Under Section 442 of the Income-tax Act, 2025, a penalty of 2% of the value of each relevant international transaction or specified domestic transaction may be imposed for specified failures, including:
- Failure to maintain prescribed information and documentation.
- Failure to report a transaction that is required to be reported.
- Maintaining or furnishing incorrect information or documents
Penalty for Failure to Furnish Information When Requested
Section 457 provides for a penalty of 2% of the value of the transaction for each such failure where a person fails to furnish information or documents required under Section 171(2), subject to the statutory provisions.
Penalty for Failure to Furnish Form No. 48
Under Section 447 of the Income-tax Act, 2025, failure to furnish the accountant’s report required under Section 172 may attract a penalty of ₹1 lakh.
Transfer Pricing Adjustments
If the tax authorities determine that a transaction was not priced in accordance with the arm’s length principle, they may determine the arm’s length price and adjust the taxable income accordingly.
This may increase the business’s tax liability.
Additional Tax, Interest and Disputes
A transfer pricing adjustment may also lead to additional tax, applicable interest and other penalties where the relevant statutory conditions are satisfied.
Businesses may also face prolonged tax proceedings, requests for additional information and disputes with tax authorities.
Maintaining reliable documentation and reporting transactions accurately can help reduce these risks.
How Can Businesses Prepare for Transfer Pricing Compliance?
A proactive approach can help companies manage their transfer pricing requirements more efficiently.
The following steps can be incorporated into the organisation’s annual tax compliance process.
Identify All Associated Enterprises
Review the ownership structure, voting rights, management relationships, financial arrangements and other statutory tests to identify associated enterprises.
Review International and Specified Domestic Transactions
Prepare a transaction register covering purchases, sales, services, royalty, loans, guarantees, cost-sharing arrangements and other relevant transactions.
For domestic transactions, verify whether they fall within the specified statutory categories and whether the ₹20 crore aggregate threshold is exceeded.
Evaluate Intercompany Pricing Policies
Review the pricing policies followed by group companies and assess whether they are commercially justifiable and consistent with the arm’s length principle.
Conduct Benchmarking Analysis
Identify suitable comparable transactions and select the most appropriate transfer pricing method based on the facts and circumstances.
Maintain Supporting Documentation
Keep agreements, invoices, financial statements, cost workings, benchmarking reports and other supporting information organised and accessible.
Review Compliance Requirements With a Tax Professional
Transfer pricing rules involve technical tax provisions, financial analysis and documentation requirements. A qualified professional can help businesses identify their obligations and prepare appropriate reports.
When Should Your Business Seek Transfer Pricing Advisory Services?
Businesses should consider professional support when their transactions with associated enterprises become more frequent, complex or financially significant.
Some situations where transfer pricing advisory services can be particularly useful include:
- Starting overseas group transactions: When an Indian company begins purchasing goods or receiving services from a foreign associated enterprise.
- Setting up an Indian subsidiary: When a multinational business establishes operations in India and needs to structure intercompany arrangements.
- Entering into service or royalty agreements: When group companies share technology, intellectual property, software or management services.
- Arranging intercompany loans: When related entities provide loans, guarantees or other financial support.
- Preparing annual documentation: When the business needs benchmarking, FAR analysis and accountant’s reporting.
- Responding to tax authority queries: When the organisation receives notices, requests for information or transfer pricing adjustments.
- Planning an Advance Pricing Agreement: When a business wants greater certainty about its transfer pricing methodology for eligible international transactions.
Professional support can help businesses evaluate transaction structures, understand compliance exposure and prepare appropriate documentation.
How Aplite Advisors Supports Transfer Pricing Compliance
Aplite Advisors provides specialised transfer pricing and international taxation support for businesses operating in India and across international markets.
Its Transfer Pricing Services cover areas such as:
- Transfer pricing advisory and transaction structuring.
- Arm’s length pricing analysis.
- Functional analysis and transfer pricing risk assessment.
- Transfer pricing documentation and compliance.
- Accountant’s reporting support under the applicable framework.
- Master File and Country-by-Country Reporting assistance.
- Advance Pricing Agreement (APA) support.
- Transfer pricing litigation and representation support.
- Assistance with Safe Harbour Rules and Mutual Agreement Procedure (MAP).
Businesses can also explore Aplite Advisors’ International Taxation Services for broader cross-border tax and compliance requirements.
Conclusion
Transfer pricing in India is an important tax compliance requirement for businesses dealing with associated enterprises through international or specified domestic transactions.
The rules require covered transactions to follow the arm’s length principle, supported by appropriate benchmarking, documentation and annual reporting.
For Indian subsidiaries of multinational companies, IT and software service providers, manufacturers and businesses involved in intercompany financial arrangements, understanding these requirements is essential.
The transition to the Income-tax Act, 2025 from 1 April 2026 also makes it important to identify the correct legal framework and reporting form for each tax year. Businesses dealing with FY 2025–26 transactions continue to follow the relevant provisions of the Income-tax Act, 1961, while Tax Year 2026–27 onwards is governed by the new provisions and Form No. 48.
With proper planning, accurate documentation and timely reporting, businesses can manage their transfer pricing responsibilities more effectively.
For organisations seeking professional assistance, Aplite Advisors offers transfer pricing advisory, documentation, compliance and international taxation support. Its team can help businesses understand applicable requirements, evaluate related-party transactions and prepare for their tax reporting obligations.
Explore Aplite Advisors’ Transfer Pricing Services to learn more about professional support for your business.
Frequently Asked Questions
Transfer pricing in India refers to the tax rules governing the pricing of transactions between associated enterprises. These rules require covered international and specified domestic transactions to be determined with reference to the arm’s length principle.
Transfer pricing rules generally apply when an Indian taxpayer enters into an international transaction with an associated enterprise where at least one enterprise is non-resident. They also apply to qualifying specified domestic transactions when their aggregate value exceeds ₹20 crore during the relevant tax year.
No. The Indian transfer pricing provisions generally apply to international transactions between associated enterprises, where at least one enterprise is non-resident. Transactions between unrelated independent businesses do not automatically become covered transfer pricing transactions merely because they are cross-border.
The arm’s length principle means that a transaction between associated enterprises should be priced as if it were conducted between independent parties under comparable circumstances. It helps ensure that related-party transactions reflect commercially appropriate pricing.
The aggregate value of qualifying specified domestic transactions must exceed ₹20 crore during the relevant tax year for the specified domestic transaction provisions to apply. The threshold does not apply to all domestic related-party transactions; the transaction must first fall within the statutory definition.
For FY 2025–26, the applicable framework is the Income-tax Act, 1961, and the accountant’s report is furnished in Form 3CEB.
For Tax Year 2026–27 onwards, the Income-tax Act, 2025 applies, and the accountant’s report under Section 172 is furnished in Form No. 48.
Non-compliance may result in penalties, transfer pricing adjustments, additional tax liability, interest and tax disputes. Under the Income-tax Act, 2025, specified failures to maintain or report transaction information may attract a penalty of 2% of the relevant transaction value, while failure to furnish the accountant’s report may attract a penalty of ₹1 lakh.
Yes. A small business may be covered if it enters into an international transaction with an associated enterprise and the statutory conditions are satisfied. There is no general minimum monetary threshold for international transactions. Specified domestic transactions, however, have a ₹20 crore aggregate threshold and must fall within the statutory categories.